ARMA: Auto Regressive Moving Average
ARMA(1,1) time series model
Xt = 0.5 Xt-1 + Zt + 0.7 Zt-1
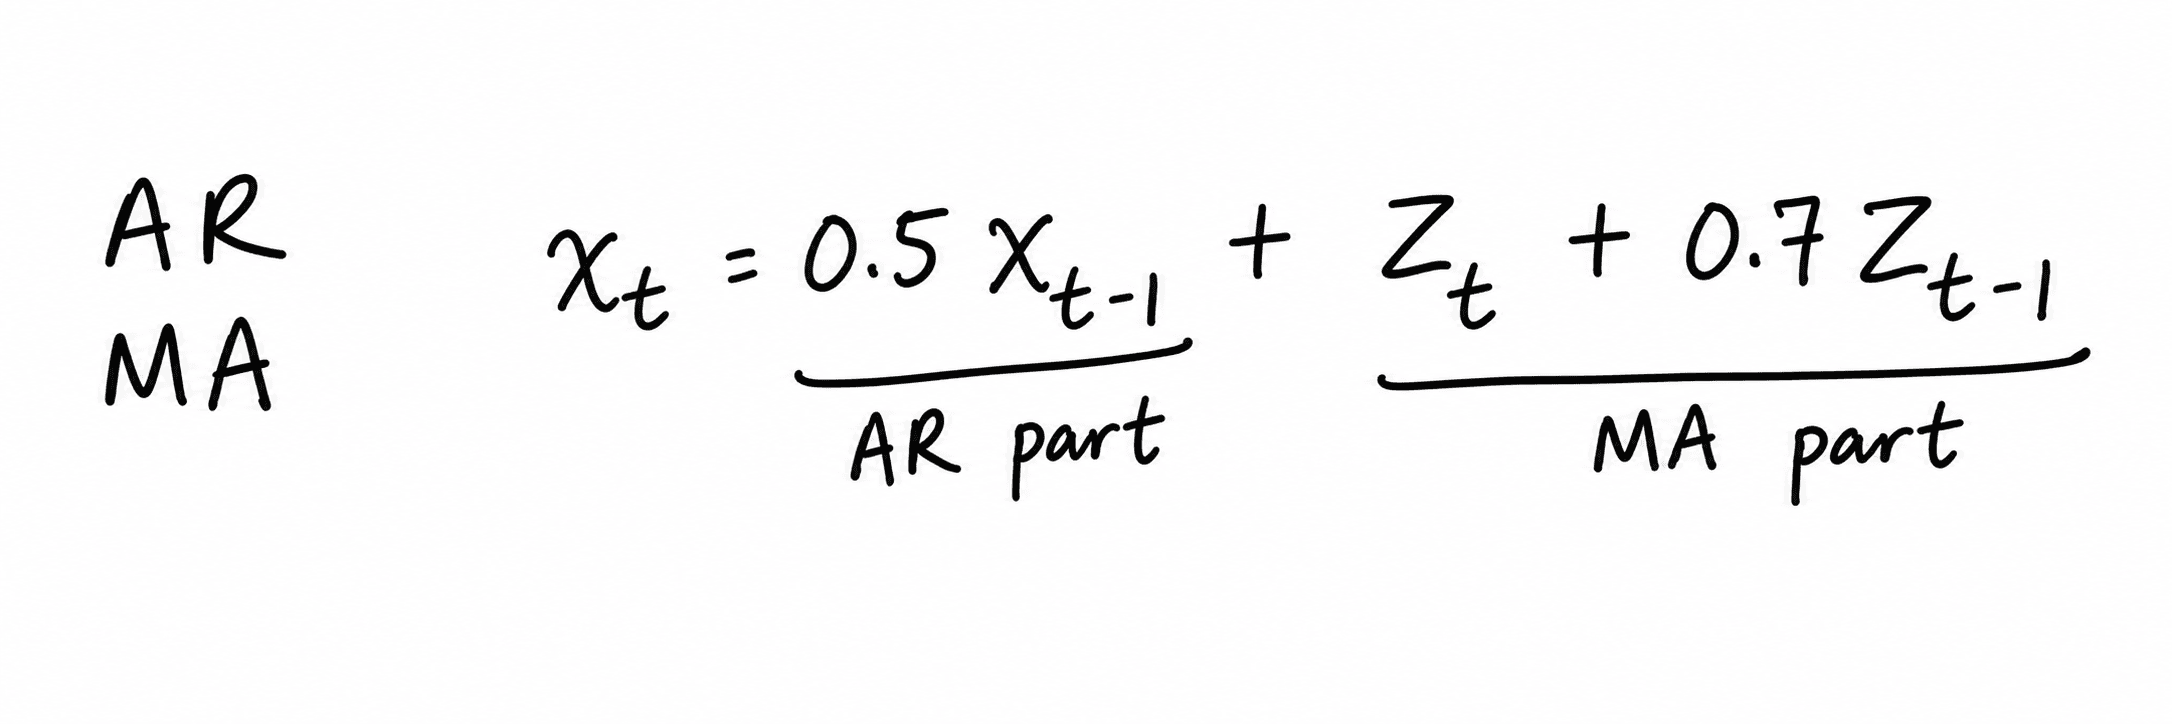
- AR order: p = 1
- MA order: q=1
- Stationarity: |0.5|<1
- Invertibility: |0.7|<1
Assuming Zt is white noise, the model is stationary and invertible.
ARMA Limitations
Anomaly Detection
Autoencoder for Anamoly Detection
Latent Space: Encoder f, Decoder g
Isolation Forest Algorithm
Gaussian Mixture Model
LSTM Long Short Term Memory
ARIMA
Auto Regressive - eg: sales depend on past sales
Integrated - Removing long term/ seasonal changes
MA - Fixing unexpected errors
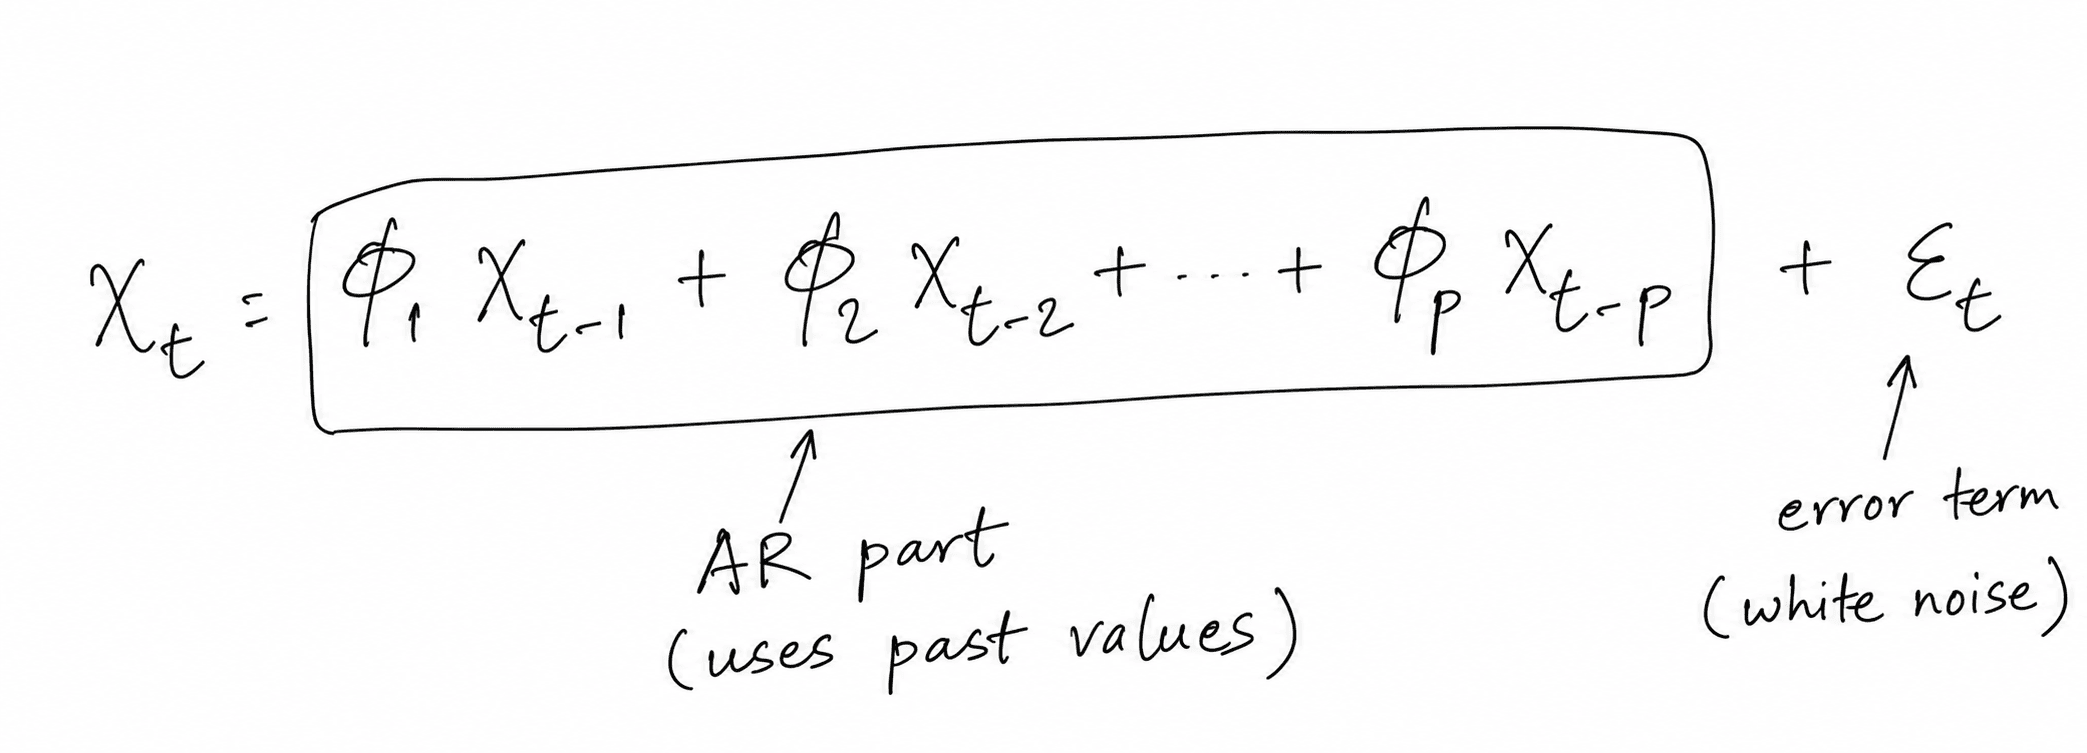
Xt : current value of series
ϕi : AR coefficients
p : order of AR process
εt : white noise (random error)
Backward Pass in RNN
GRU / LSTM
RAE, RCNN and RvNN
Autocorrelation
- sequential data : text and language, audio
- analysis methods :
- decomposition
- correlation analysis
- smoothing
- forecasting
- window function
- STFT - short time fourier transform
- types of window
- adjacent
- overlapped
- hop size (25%)
- co-integration
- auto-covariance and auto-correlation